Selling your home for cash promises speed, simplicity, and freedom from bank approvals. But in today's real estate market, anyone can claim to be a cash buyer. Some are legitimate local home buyers, while others are middleman wholesalers trying to tie up your contract without having a single dollar in the bank.
Demanding and verifying a cash buyer proof of funds is your single best defense against cancelled contracts, wasted months, and wire fraud. If you are selling a home in Ventura County, here is exactly how to protect yourself and ensure your buyer can actually deliver on their promise.
Understanding Cash Buyer Proof of Funds
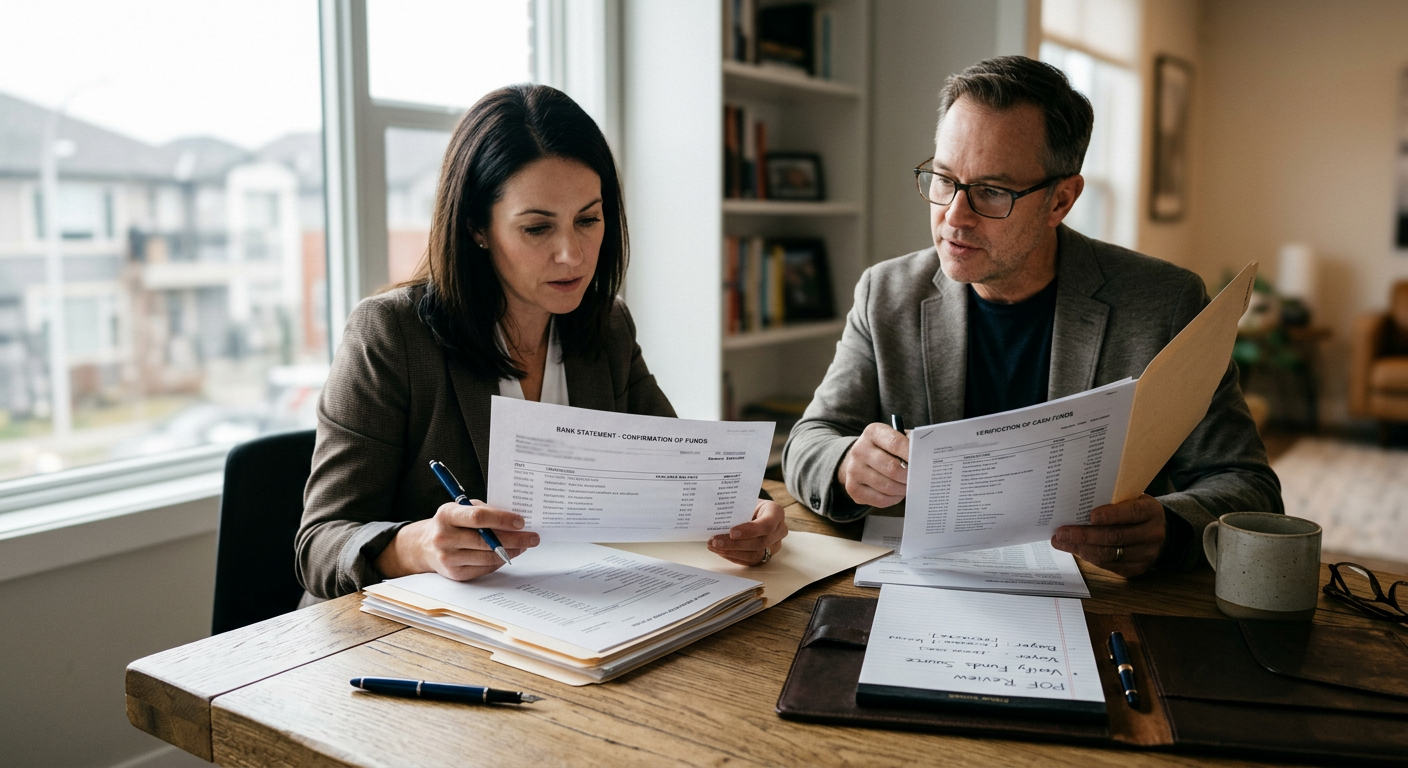
A proof of funds (POF) is a document or collection of documents that proves an individual or business entity has enough liquid funds available to complete a real estate transaction. In a cash home sale, there is no mortgage company backing the purchase. The buyer's bank account is the lender.
Without a verified POF, accepting a cash offer is a major financial risk. If the buyer cannot produce liquid cash at escrow, your home sits off the market for weeks. You lose time, accumulate holding costs, and risk watching a clean sale fall apart.
Acceptable forms of proof of funds include:
- Official Bank Statements: A recent checking, savings, or money market account statement showing liquid cash.
- Bank Verification Letter: A formal letter on bank letterhead signed by a bank officer confirming available account balances.
- Custodial Investment Account Statements: Liquid cash equivalents held within brokerage accounts, provided they can be liquidated instantly without restrictions.
Documents that are NOT true cash proof of funds include pre-approval letters from hard money lenders, lines of credit, stocks, retirement accounts subject to withdrawal penalties, or letters from private individuals claiming they will provide the money later.
Why Verifying Cash Matters in Ventura County
The Ventura County real estate market is high-value and fast-moving. With a county-wide median home price near $920,000, selling your property involves serious money. Whether you own a home in Oxnard, a suburban property in Thousand Oaks, or a coastal ranch in Santa Paula, a failed transaction costs real time and money.
Nationwide, around 41.7% of all U.S. home purchases are cash transactions. However, traditional retail deals subject to mortgage financing carry up to a 15% fall-through rate due to sudden appraisal shortfalls or loan denials. Cash sales eliminate mortgage contingency risks—but only if the buyer's money actually exists.
Fake cash buyers generally fall into two categories:
- Unfunded Wholesalers: They sign a purchase agreement claiming to pay cash, hoping to assign the contract to a real investor for a fee before escrow closes. If they fail to find a real buyer, they cancel the deal using inspection loopholes.
- Scammers using altered PDFs: Fraudulent entities use photo editing software to create fake bank balances from foreign or non-existent institutions.
Verifying funds up front protects your equity, preserves your selling timeline, and ensures you aren't left starting over from scratch.
How to Verify Proof of Funds Step-by-Step
Verifying a cash buyer's ability to pay does not require a real estate degree. You or your closing representative can follow a straightforward verification checklist.
Want to know what we'd pay for your home?
No pressure, no obligation — just an honest number in 24 hours.
Step 1: Check the Document Date and Names
Ensure the statement or bank letter is dated within the last 30 to 60 days. An account balance from six months ago does not prove available money today. Crucially, the account holder's name must match the name on the purchase agreement or the legal LLC purchasing the property.
Step 2: Confirm Account Liquidity
The funds must be held in liquid cash, checking, savings, or money market accounts. If the buyer provides an investment statement, ensure the assets aren't tied up in illiquid real estate, restricted stock, or private equity.
Step 3: Contact the Issuing Bank Directly
Do not call the phone number printed on an unverified PDF letter provided by the buyer. Look up the bank’s public customer service or branch phone number online. Call and ask to speak with the officer who signed the letter to confirm its authenticity and that the balance remains in good standing.
Step 4: Work With an Independent Escrow Officer
Never send signed deeds or transfers directly to a cash buyer. Always open escrow with a licensed, independent California title and escrow company. The escrow officer will demand proof of funds and hold the buyer’s initial earnest money deposit in a secure account before proceeding.
At The Higher Offer, we encourage sellers to read about how the process works so they feel confident at every step. We provide transparent, local bank proof of funds right alongside our cash offers.
What You Keep vs. What You Lose Listing Traditionally
Selling directly to a legitimate, verified cash buyer eliminates the heavy overhead expenses associated with listing a high-value home on the open market.
On a typical $920,000 home in cities like Camarillo or Simi Valley, traditional listing costs add up fast:
- Real Estate Agent Commissions (5–6%): $46,000 to $55,200 out of your pocket.
- Seller Closing Costs (1–2%): $9,200 to $18,400 in escrow, county transfer taxes, and title fees.
- Repair & Inspection Demands: Easily $10,000 to $30,000+ to satisfy retail buyer lenders.
When you work with a direct local cash buyer like The Higher Offer, you pay 0% in agent commissions and zero closing costs—we pay all of them for you. You make no repairs, host no public open houses, and close entirely on your timeline.
Ventura County Real Estate Market Context
Navigating the market in local communities like Moorpark, Fillmore, or Ojai requires understanding current home values. With average days on market sitting around 26 days for traditional listings, adding a 30-to-45-day escrow window means a traditional sale often takes two to three months from start to finish.
If you are dealing with inherited property in Newbury Park, navigating divorce in Westlake Village, or trying to sell a tenant-occupied rental in Port Hueneme, waiting months for buyer financing is rarely ideal. Verified cash sales offer speed and guaranteed closing terms that retail listings simply cannot match.